
UNest: Invest & Save for Kids
- Rating
- 3.8
- Downloads
- 100.00K
- Content Rating
- Everyone
UNest: Invest & Save for Kids - Screenshots
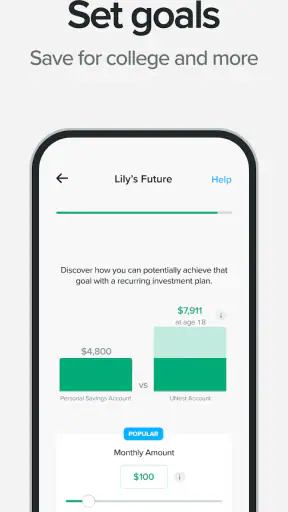
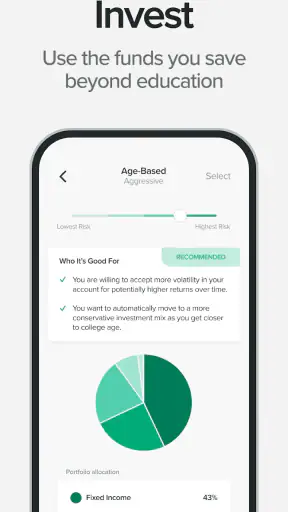
Pros
- Automated deposits make consistent saving easier for busy parents.
- Goal tracking helps families monitor progress toward future expenses.
- Investment options can support long-term growth beyond a regular savings account.
- Parents can manage multiple child accounts from one dashboard.
- Useful educational tool for introducing children to saving and investing.
Cons
- Investment returns are not guaranteed and account values can decline.
- Fees may reduce returns
- especially on smaller balances.
- Some features and account types may depend on eligibility or location.
- Transferring funds out may involve processing times or account restrictions.
- Parents should review tax and custodial implications before opening an account.
UNest: Invest & Save for Kids - Description
- App Name
- UNest: Invest & Save for Kids
- Package Name
- com.unest.android
- Developer
- UNest Holdings, Inc.
- Category
- Finance
- Last Updated
- Nov 27, 2019
- Version
- 3.8.1
Saving for a child sounds simple until the money has to move from an adult’s everyday budget into an account designed for the child’s future. UNest: Invest & Save for Kids is built around that exact handoff. It is a finance app from UNest Holdings, Inc. that helps parents and other adults save and invest through a UTMA custodial account. After spending time with it, I see the appeal: it turns a vague goal such as “start something for my child” into a guided financial routine.
That convenience is also the app’s central trade-off. This is not a general-purpose brokerage for people who want to choose individual investments, compare every possible account type, or manage a detailed portfolio. It is aimed at adults who want a simpler route to putting money aside for a child. If that describes your situation, the focused design can feel reassuring. If you already understand custodial accounts and want maximum control, the same simplicity may feel restrictive.
From an unfinished savings goal to a child-focused account
The starting condition for many families is familiar: there is a child, a long-term intention to save, and no consistent system. A separate bank account may keep cash organized, but it does not automatically create an investing habit. A standard brokerage account can offer more flexibility, yet it leaves the adult to research account structures, select investments, and maintain the plan. UNest places the custodial-account idea at the center instead of treating it as an advanced option hidden behind a broader investing platform.
I would approach the app with one question first: am I comfortable saving for a child through a UTMA arrangement rather than simply holding money in my own name? That distinction matters. A custodial account is connected to the child’s benefit, so this is not just a labeled pocket in a parent’s personal finances. The app makes the child-focused purpose easy to understand, but the adult still needs to think carefully about ownership, control, and how the arrangement fits the family’s wider financial plan.
The app is free to download and is listed for Everyone, which makes the first step approachable for a broad audience. Its current version is 3.8.1, and it works on Android starting with version 7.0. The free entry point is useful for someone who wants to inspect the workflow before committing to a regular habit, although in-app purchases range from $4.99 to $149.99 per item. I would therefore treat “free” as the cost of access, not as a promise that every optional part of the experience has no charge.
That distinction is worth keeping in mind before connecting the app to a real savings plan. A child’s account is a long-term decision, and the right question is not simply whether the interface is pleasant. I would also ask whether the account structure suits the intended recipient, whether the investing approach matches my comfort with market movement, and whether any optional purchase delivers enough value for my particular family.
Setting up the first contribution
The most useful way to use UNest is to begin with a specific purpose rather than an abstract wish to invest. For example, I might decide that money received for birthdays, a small monthly amount, or occasional family contributions should go toward a child’s future. Defining that purpose before opening the account helps prevent the app from becoming another financial dashboard that I check without taking action.
Once the adult has chosen the child and the reason for saving, the process becomes a sequence of handoffs. The adult supplies the information needed to establish the custodial relationship, decides how contributions should be made, and then lets the account become the destination for those funds. The app’s value is less about making one dramatic investment decision and more about reducing the number of decisions required every time money is available.
I like this approach for a busy parent because the account can be treated as a separate lane in the household budget. Instead of remembering to transfer money after every payday or gift, I can make the contribution part of a repeatable routine. The important practical tip is to start with an amount that can survive an ordinary month. A smaller contribution maintained consistently is more useful than an ambitious plan that gets abandoned after an unexpected bill.
Another helpful workflow is to separate “money intended for the child” from “money needed by the household.” That sounds obvious, but mixing the two makes long-term saving emotionally difficult. If I use the app, I would decide in advance which funds are genuinely child-directed and avoid treating the custodial account as an emergency reserve. The app can organize the goal, but it cannot replace a household emergency fund or solve a cash-flow problem.
What happens after money enters the plan
UNest is designed to connect saving with investing, so the outcome is not merely a balance sitting in a conventional savings account. That can be valuable for a long horizon, because the account is intended to build wealth over time rather than serve as a short-term spending wallet. It also introduces market risk. The balance can move, and a parent who expects every contribution to remain stable may be uncomfortable when investments fluctuate.
This is where I would resist judging the app by a single day’s result. A custodial investment account needs to be considered over the period for which the money is intended. At the same time, “long term” should not become an excuse to ignore the account. I would review contributions, confirm that the child information remains correct, and check whether the chosen approach still fits the goal as the child gets older.
The app’s guided nature may help people who would otherwise leave money uninvested because the alternatives feel complicated. It is particularly suitable for a first-time saver who wants a child-specific destination without learning every feature of a full brokerage platform. The trade-off is that a guided experience may not provide the same sense of control as a self-directed account. Someone who wants to select individual securities, build a custom allocation, or use advanced research tools should look elsewhere.
I also would not use it as a substitute for teaching a child about money. The account can support a financial goal, but the learning outcome depends on what the family does around it. A parent could use contributions as a chance to explain saving, investing, patience, and risk. Without that conversation, the app may remain an adult-managed container that the child knows little about.
The handoffs that determine whether the workflow works
The first handoff is from intention to adult action. A relative may say they want to help a child, but someone still has to create the account and manage the contribution. That makes UNest more useful when one responsible adult is willing to own the routine. If everybody assumes somebody else will handle it, the app cannot create momentum by itself.
The second handoff is from the adult’s bank balance to the custodial account. This is the point where convenience matters most. A smooth contribution process can turn occasional generosity into an organized plan. A confusing or overly demanding setup can stop the workflow before the first investment occurs. My advice is to complete the initial setup when I have the relevant personal and child information available, rather than starting casually and expecting to finish later.
The third handoff is from the account to the child’s eventual benefit. This is also the part that deserves the most thought. The money is being set aside for the child, not simply tagged with the child’s name for convenience. Before contributing a large amount, I would make sure I understand the implications of using a UTMA custodial account and how it fits with other goals, such as education costs, general financial support, or a parent’s retirement.
That last comparison is important. Saving for a child should not put the adult’s own basic financial stability at risk. If I have high-interest debt, no emergency savings, or no retirement plan, I would be cautious about making a child-focused investing app the next priority. UNest can make a dedicated goal easier, but it cannot make an unaffordable contribution sensible.
A realistic everyday scenario
Imagine a parent who receives a modest birthday gift for a six-year-old and wants the money to have a longer life than a toy purchase. The parent opens UNest, uses the custodial-account workflow to establish the child’s account, and treats that gift as the first contribution. Later, the parent adds a manageable amount during the month instead of waiting for another special occasion. Grandparents or other relatives can be told that the family has a dedicated destination for child-directed money, reducing the chance that every contribution becomes an unplanned purchase.
The benefit in this scenario is behavioral. The app gives the parent a visible place for the goal and a reason to keep the process separate from daily spending. The outcome is not instant wealth; it is a repeatable system that can continue while the child is young. The weakness is equally realistic: if the parent’s income varies, the contribution habit may be interrupted, and the investment balance may not behave like cash when the family suddenly needs money.
I would also set a calendar reminder to review the plan at sensible intervals rather than checking it constantly. Frequent checking can encourage emotional reactions to market movements, while never checking can allow outdated assumptions to persist. A short review can confirm that the account still serves its purpose, that contributions remain affordable, and that the adult understands where the money stands.
Where the simple flow starts to break
The workflow becomes less comfortable when the user wants answers beyond the app’s focused purpose. A person comparing a UTMA custodial account with other ways to save may need broader financial guidance than a dedicated children’s investing app is meant to provide. I would not choose UNest as my only source of education for tax planning, financial aid considerations, estate planning, or a complicated family situation.
It can also be the wrong fit for short-term goals. If the money is needed soon, investing introduces uncertainty that a cash-based option may avoid. The app’s child-focused presentation can make the goal feel organized, but organization does not remove investment risk. For a near-term purchase or an emergency, I would prefer an appropriate cash reserve rather than relying on a market-linked account.
Another friction point is the cost of optional purchases. The app’s free availability lowers the barrier to trying it, but the range of in-app purchase prices means I would inspect each paid option carefully before accepting it. A feature is worthwhile only if it improves my actual saving behavior or understanding. Paying for something simply because it appears during setup would undermine the app’s main purpose.
The rating gives a useful but imperfect signal: UNest holds an average of 3.8 from around 2.5 thousand ratings, with roughly 430 written reviews. It has passed 100 thousand installs, so it is not an obscure experiment, but those figures do not decide whether it suits my circumstances. Finance apps are judged heavily by personal expectations, account needs, and comfort with investing. I would read recent user feedback for recurring setup or support concerns while remembering that another person’s account structure may differ from mine.
How it compares with the usual alternatives
Compared with a regular savings account, UNest offers a more direct connection between a child-focused goal and investing. A savings account is easier to understand for short-term stability and may be preferable when preserving the contribution is the main priority. UNest is more compelling when the goal is long term and the adult accepts that investment values can rise and fall.
Compared with a standard brokerage account held by the parent, the custodial approach gives the child’s purpose a clearer legal and organizational identity. That can reduce the temptation to spend the money elsewhere. A parent-owned brokerage account may be more flexible for changing family priorities, however, and may offer a wider selection of tools. The better choice depends on whether dedicated structure or personal control matters more.
Compared with a do-it-yourself brokerage, UNest is less demanding at the beginning. Someone who does not want to research every investment choice may appreciate that. The same person should still learn enough to understand the account’s purpose and risks. Simplicity is helpful when it removes unnecessary friction; it is harmful when it encourages a user to invest without understanding what they are agreeing to.
Compared with a specialized education savings route, UNest appears more general in its child-wealth framing. That can be useful when the family wants the money to support a broader future rather than a single expense. If education is the only objective, I would compare the relevant account types before choosing. A child-focused label alone does not guarantee that one account is best for every future use.
Who should use it and who should pass
I would recommend UNest to a parent, grandparent, or other adult who wants a dedicated investing routine for a child and prefers guided simplicity over a large menu of financial tools. It is especially appealing for someone who has delayed saving because opening and managing a conventional investment account felt intimidating. The free download and Everyone content rating make it easy to begin exploring the idea.
I would be more cautious if the adult is unsure about custodial ownership, expects to need the money soon, or wants total control over individual investments. I would also skip it as a first move if my own finances were unstable. In those cases, a cash reserve, debt repayment, retirement contribution, or a conversation with a qualified financial professional may deserve attention first.
My practical recommendation is to use the app as a system, not as a one-time gesture. Decide what the account is for, choose a sustainable contribution, understand the UTMA handoff, and review the plan occasionally. Do not confuse a friendly interface with a guarantee of returns, and do not let a child’s goal become an excuse to ignore the adult’s financial foundation.
My final take after following the full workflow
UNest succeeds when the problem is not a lack of good intentions but a lack of structure. It takes the path from “I should save for this child” to a dedicated custodial investing account and makes that path feel less intimidating. The strongest part is the clear connection between the adult contributor, the child, and the long-term purpose.
Its limitations are the natural cost of that focus. Users who need broad financial planning, detailed investment control, short-term cash safety, or maximum flexibility may find a bank account, a parent-owned brokerage, or another specialized option more suitable. Optional in-app purchases also deserve a careful look before spending.
Overall, I see UNest as a practical starting point for a family that wants to build a child-focused habit and is prepared to understand the responsibility behind a UTMA account. The best result comes from pairing the app’s simple workflow with deliberate decisions about affordability, time horizon, and ownership. Used that way, it is more than a place to deposit money: it is a reminder to turn a hopeful future plan into a routine the household can actually maintain.
FAQ
What is UNest: Invest & Save for Kids, and how does it work?
UNest is a family-focused investing and savings app designed to help parents and relatives build money for a child’s future. After creating an account, you can set up recurring contributions, invite family members to participate, and invest through an account intended for the child. The app is designed to simplify long-term saving, although investment results are never guaranteed.
Is UNest a safe and legitimate app for saving money for children?
UNest is designed to provide a structured way to save and invest for a child, but users should still review the company’s current disclosures, account agreements, privacy policy, and regulatory information before depositing money. Investments can lose value, and account protections may differ depending on the product used. Download the app only from an official store and verify the provider details.
What type of account does UNest provide for a child?
UNest generally focuses on investment accounts intended to benefit a minor, commonly using a custodial account structure. The adult opening the account manages it while the child is under the applicable legal age, and control may eventually transfer according to state rules and account terms. Because eligibility, ownership, and transfer requirements can vary, read the current terms carefully.
How much does UNest cost, and are there any additional fees?
Before signing up, check UNest’s latest pricing because subscription charges, management fees, investment expenses, and promotional terms may change. Some plans may include a recurring membership cost, while the underlying investments can also have their own expenses. Compare the total annual cost with the amount you plan to contribute, especially if you are starting with small deposits.
Can grandparents, relatives, or friends contribute through UNest?
One of UNest’s useful features is the ability to involve family and friends in a child’s savings goals. Depending on the current version and account setup, invited contributors may be able to make gifts or deposits without managing the entire investment account. Confirm contribution limits, payment methods, gift rules, and whether the recipient needs an UNest account before sending money.


